Protecting Every Future is a program of The American Council of Life Insurers.
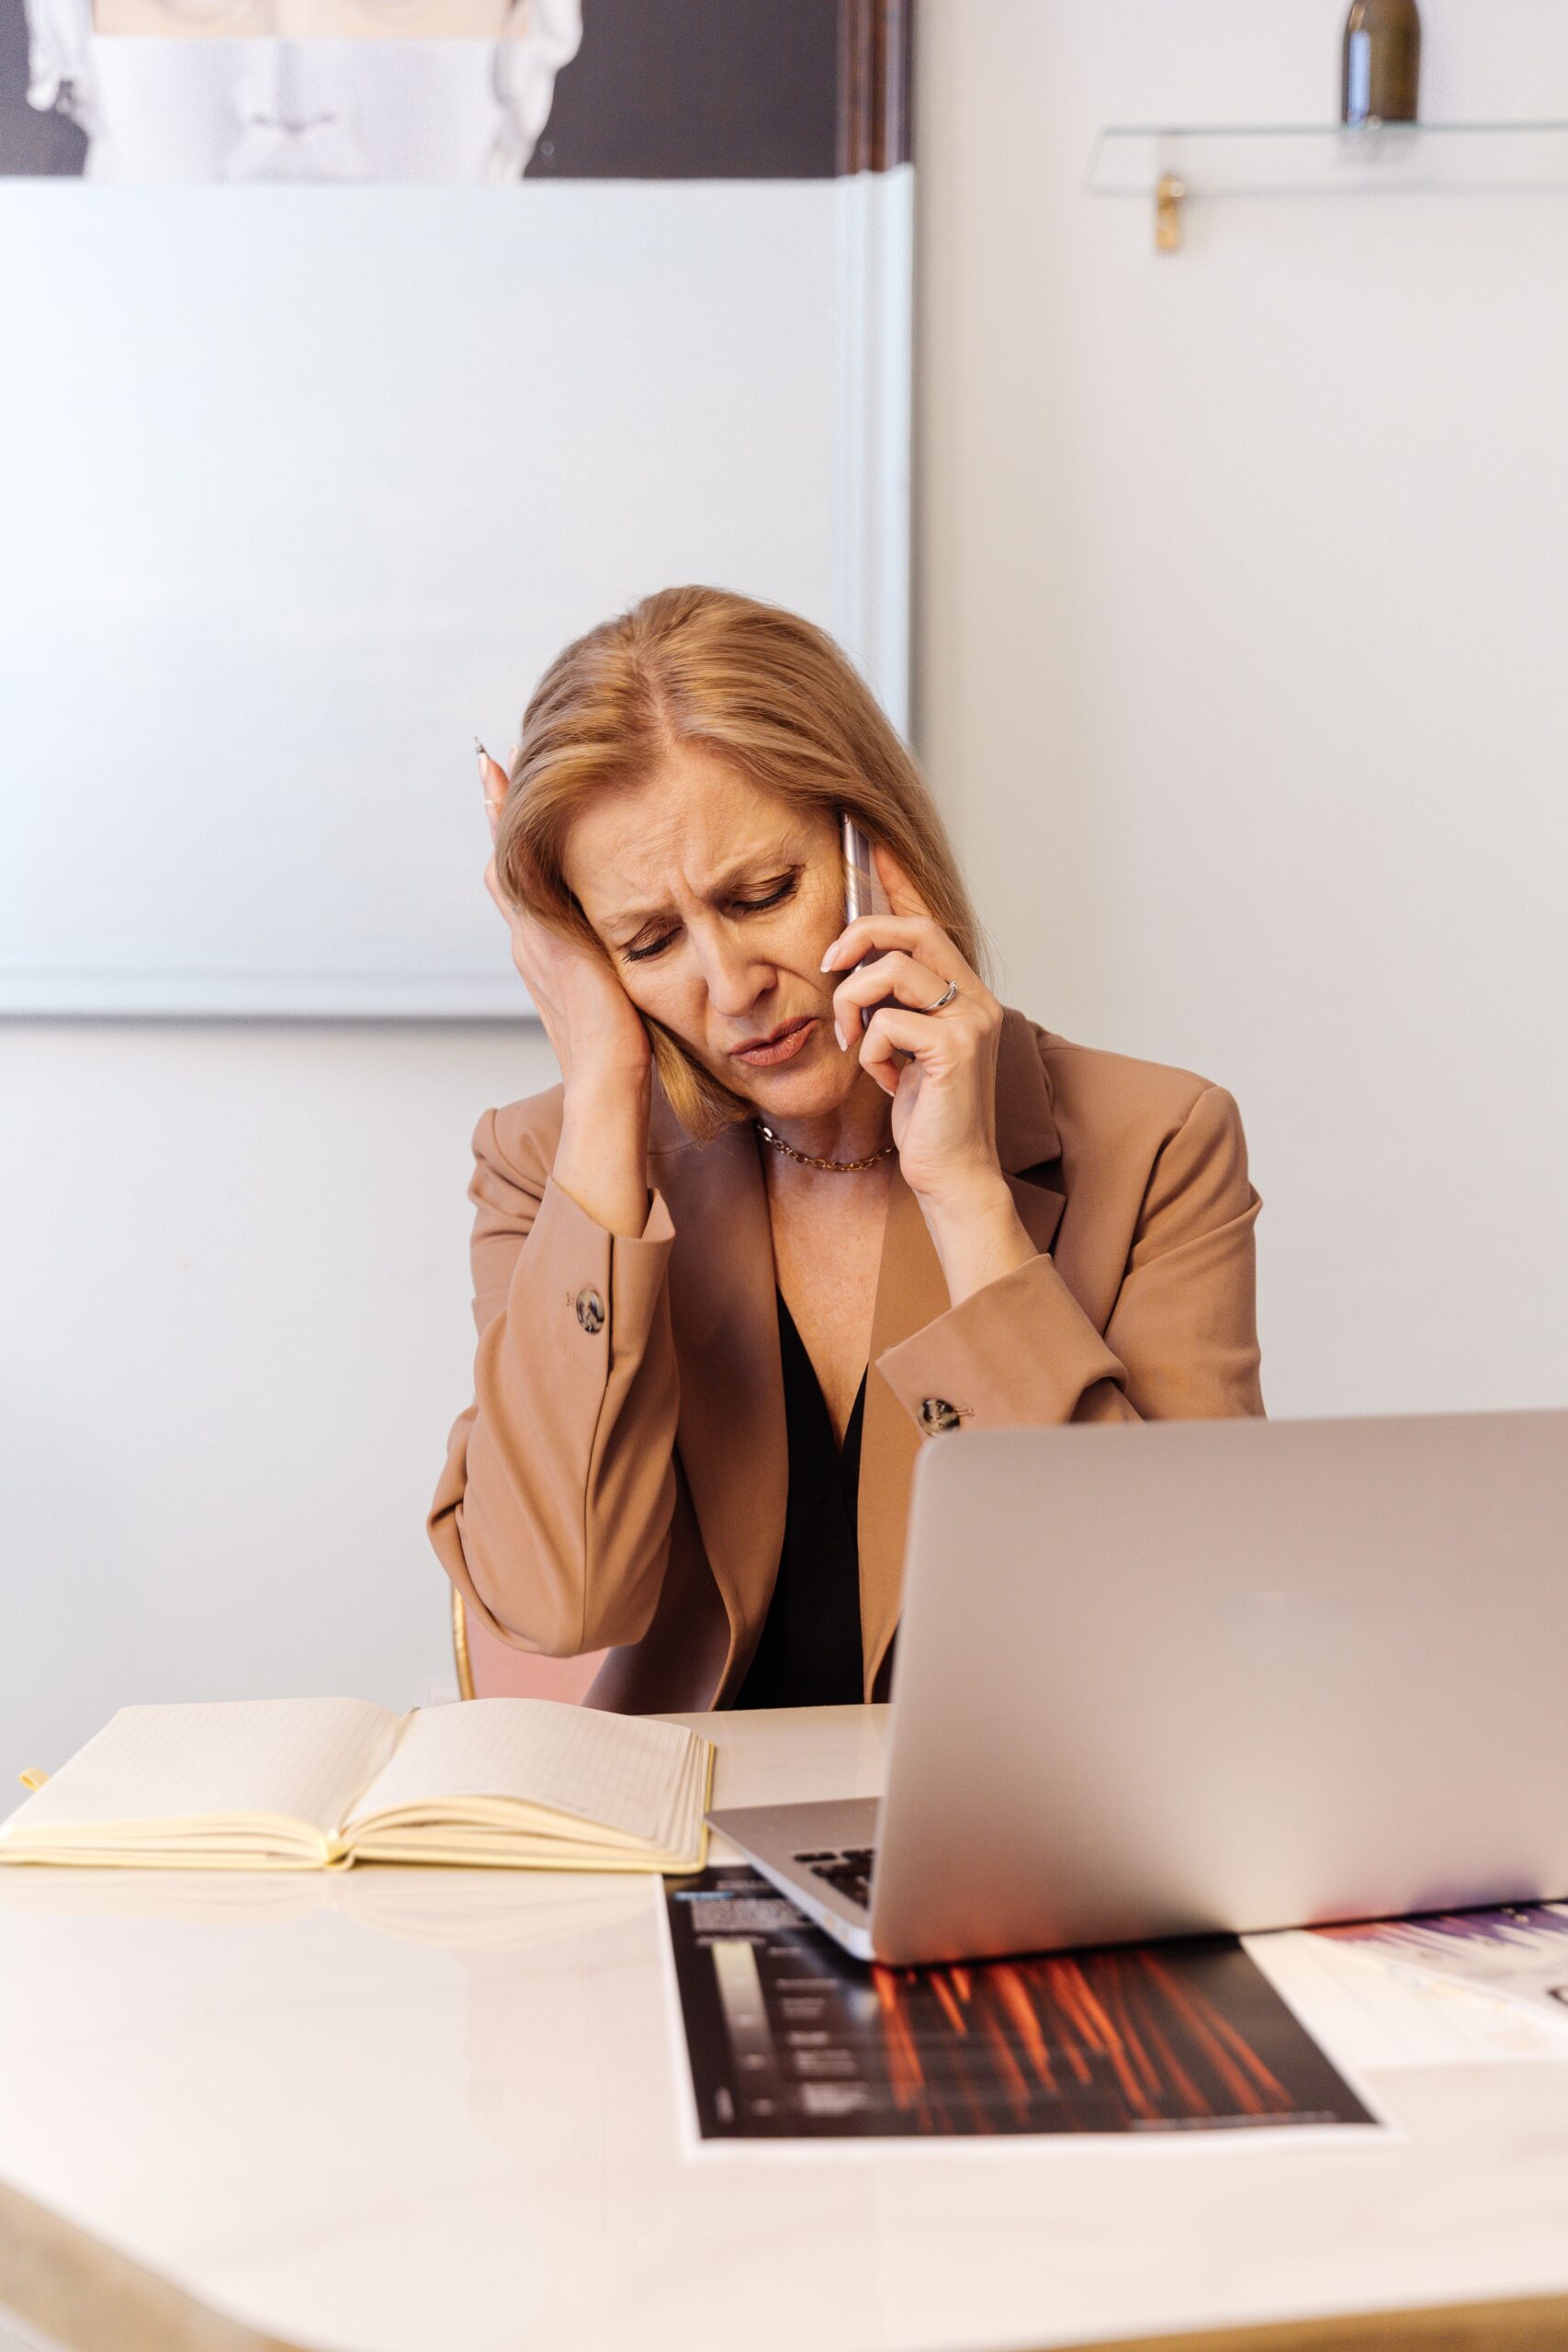
Your Retirement Could Change with One Phone Call
A parent falls. A spouse receives a difficult diagnosis. A loved one suddenly needs help.
In a moment, the retirement you’ve spent years planning can look very different. Thoughts of travel, hobbies and financial goals can quickly give way to questions about home health needs, work schedules and unexpected expenses.
Caregiving is often viewed as a family or health issue. New research shows it’s also a retirement security issue.
Greater Financial Challenges
According to new research, 34% of caregivers have less than $10,000 in savings and investments compared with 25% of non-caregivers and are more likely to say debt was a problem.
For those still working, the impact can reach even further. More than half said it negatively affected their ability to save for emergencies or work the hours they wanted or needed. Retirees were also more likely to have left the workforce earlier than planned because they needed to care for a spouse or family member.
The Cost Families May Not Expect
39% of middle-class households say they plan to rely on Medicare to pay for long-term care. While Medicare may cover certain skilled nursing services when requirements are met, that’s different from ongoing long-term care services like daily assistance with bathing and dressing.
When families aren’t prepared, the consequences can extend to caregivers, with 34% reporting they provide financial support to the person receiving home health assistance, while 20% have taken on new or additional debt because of caregiving.
Families Can Understand Their Options Before That Phone Call Comes.
Looking after a loved one may be one of the most meaningful things we ever do. It can also become one of a family’s biggest financial challenges when planning for retirement.
Understanding financial options, and preparing before caregiving needed can help families protect both the people they love and the financial futures they’ve worked hard to build. Here are a few resources to learn more:
- Depending on the policy, long-term care insurance can help cover qualifying nursing home, assisted living or home health expenses.
- Life insurance with long-term care benefits can provide another option for certain qualifying expenses.
- Annuities can be structured to provide guaranteed lifetime income in retirement.
###